Distressed Properties: High Risk, High Reward—And Right for You?
Dusty Rhodes • December 13, 2021

Are you looking to save some money? Do you need a property and don’t mind doing some repairs to get you started? Do you want to start investing in property? Well, look no further—distressed properties might be just what you need.

What is a distressed property?


To better understand this, let’s examine how a property gets to a state of foreclosure.


An individual wants to buy a house, so they will approach mortgage companies or financial institutions to get a loan. After the loan is approved, it is the individual’s responsibility to ensure that they meet the regular payment agreement that they made with the mortgagee.


However, if the homeowner fails to meet the agreement, the mortgagee or lender will want to get back the money they have provided to the homeowner. This process is what we refer to as foreclosure or repossession. This can happen for many reasons, like a divorce or bankruptcy.


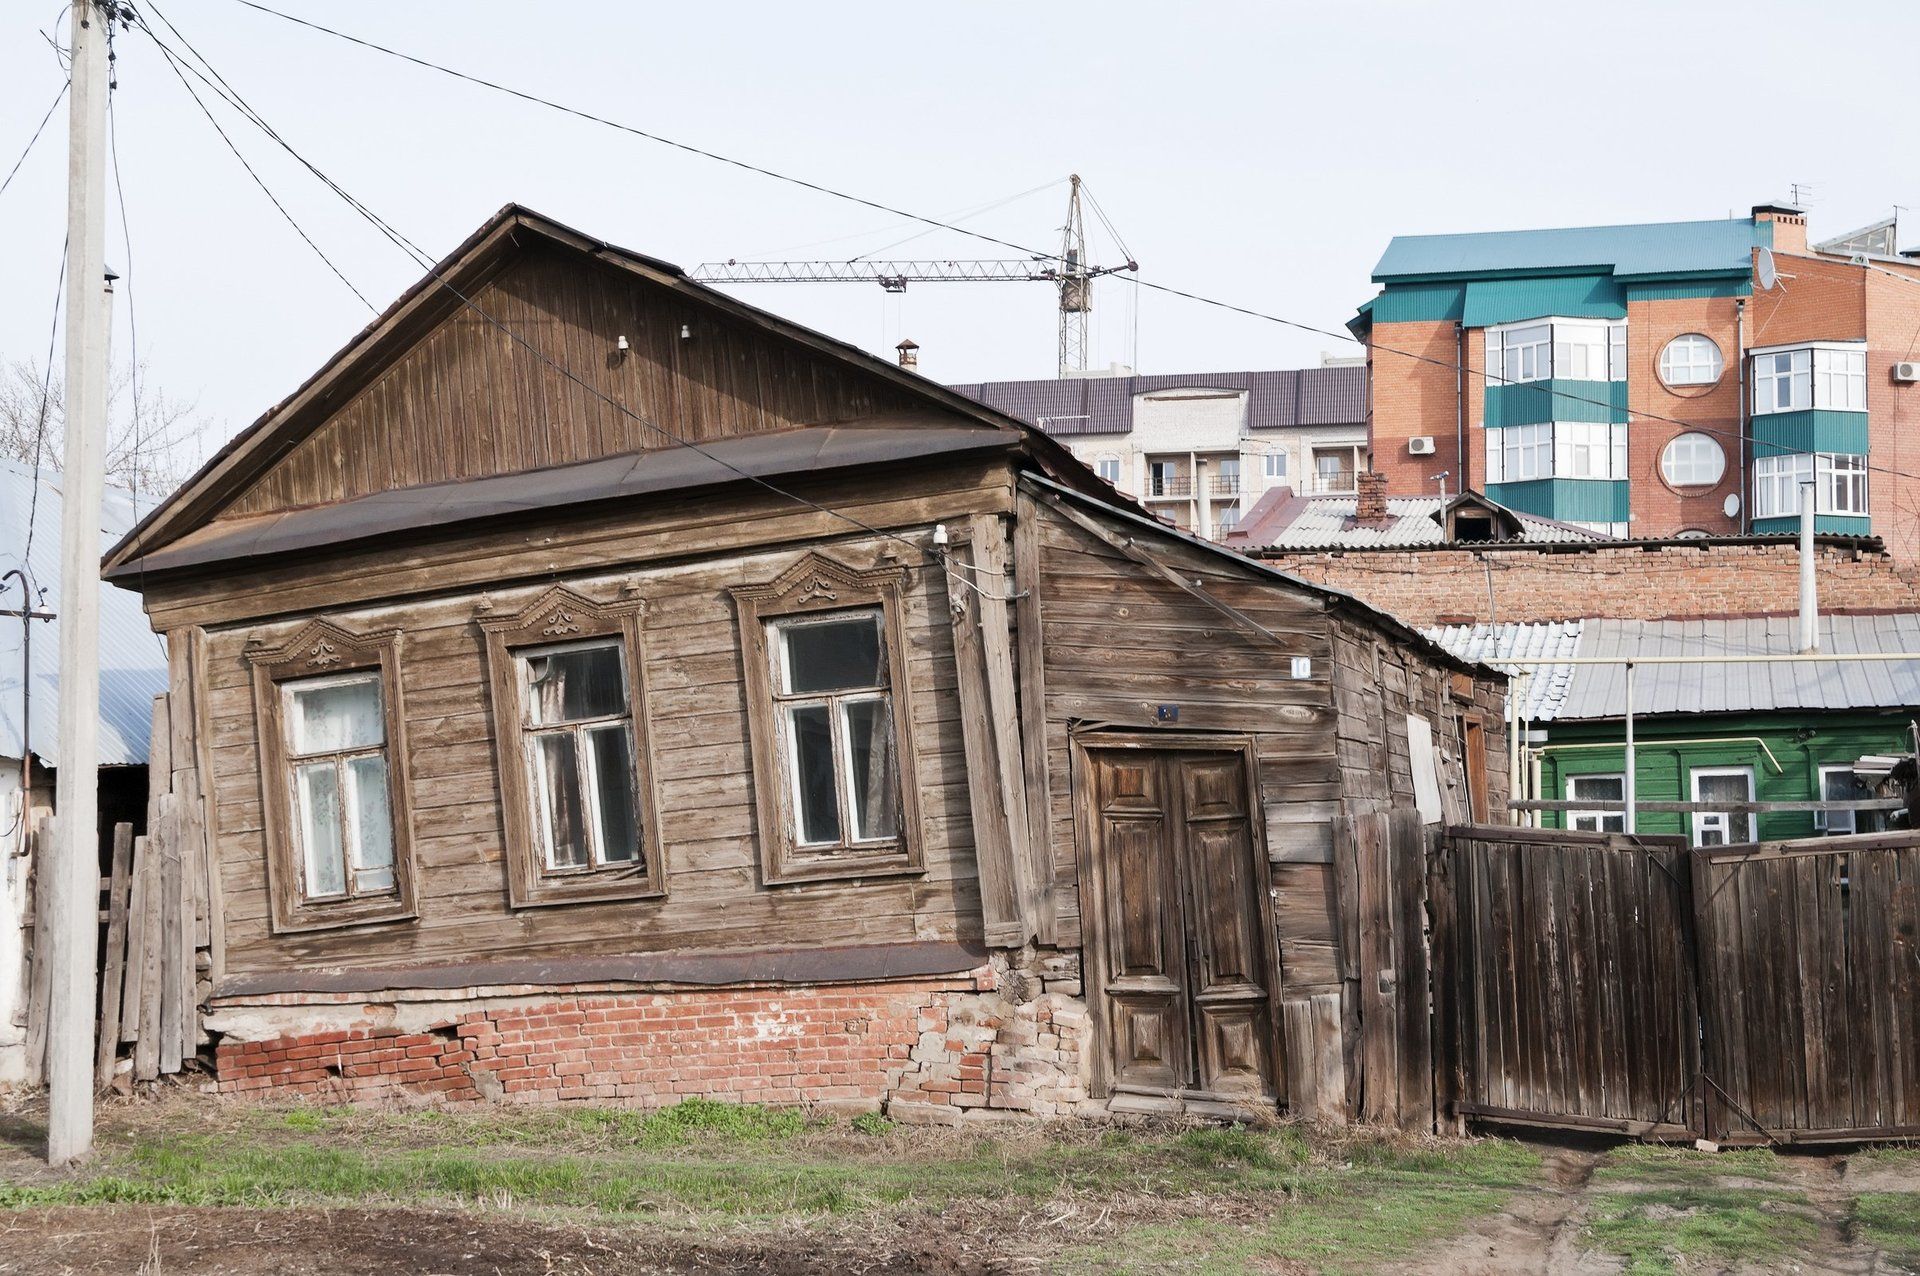
There are also instances where houses are distressed because of the state of the property—that is, old homes that need repairs or buildings that are mid-construction and were halted because the owners ran out of money and weren’t in a position to complete the construction.


REOs are bank-owned properties that have already been foreclosed and are siphoning money from the banks that own them. Owners of these properties are very motivated to sell because they want them to stop costing them money.


Short sale properties are those whose owners are often in financial distress, can’t afford the mortgage payments and lack the assets to pay off the loan, and are willing to sell the property for a discount—less than the amount due on a mortgage. This can be a good way to flip a house and sell or rent it out for a profit.


And that’s exactly what distressed properties are. They are homes that are for sale not because the owner wants to sell but because of pre-foreclosure, foreclosure, repossession, real estate owned by a lender, (REO) or personal financial reasons. These homes are usually offered up through an auction in which the highest bidder gets the property.


These houses are usually offered way below market value. Basically, all parties are trying to cut their losses.


If you consider the actual cost that goes into trying to sell something for a good price, lenders want to make sure they don’t have to invest a ridiculous amount of money or time trying to get that extra dollar. That means low prices. All they want to do is get at least some of their money back.


This also means that these properties usually have work to be done. Most likely, the previous owner wasn’t able to carry out maintenance on the property because they were short on funds. Unfortunately, some homes really look pretty awful and need a lot of work.


Risks of buying a distressed property


Buying a distressed property can be a great real estate investment, allowing you to net a large profit off of a property that’s listed below market value. But although there are plenty of benefits that come with it, there are also risks.


The biggest one is buying the property as-is. Distressed properties usually come in bad shape and are sold as they are without a proper inspection. Plus, you can’t often negotiate for things like repairs or additions, as the seller doesn’t have much wiggle room in their budget. You’ll have to take on that maintenance yourself.


You may also be outbid at an auction for the property, a likely scenario for a distressed property. These properties are often a good value, which can mean more competition from other buyers.


Purchasing delays can be an issue as well. The purchasing process takes a relatively long time since the sale is a little less straightforward when working with a seller who is in debt on their mortgage. It can take months to finalize, and you may have to jump through hoops along the way to help the sale go through.


Why invest in distressed real estate?


Consider the disadvantages associated with building a new property, such as the time, permits, construction loans, and legal implications.


With the purchase of a distressed property, your core focus is on your ability to get a good bargain and maximize your investment returns.


Here are three reasons to invest in distressed real estate.


1. Lower prices

Due to the nature of distressed properties, it is easy to get a property below market value. You can easily buy distressed properties all across the Midwest from 10 to 20 cents on the dollar, which is one-third of the cost of building a new property—although be mindful that you may have to seek these properties out yourself.


This is because homeowners are usually in a position where they really want to sell—fast. That places you in a better position to get a bargain. Combining the position you’re in with negotiation talent is guaranteed to save you a lot of money going forward. If you’re looking to build a portfolio, that’s exactly where you want to be.


2. Financial gain

Distressed properties create opportunities for real estate investors to make a profit. Because the prices are below market value, your margins are simply a lot better with distressed properties.


That also means that you’re taking on far less risk. If you can buy two properties for the price of one, not being able to sell one of them might not be much of a problem. You’ll just hold on to it longer. Having less financial pressure comes with more freedom.


The law of home equity states that as the value of your property grows, your equity increases. With the purchase of distressed properties, you are instantly in a position to get yourself some great financial gain because you have bought a house for a value lower than its market value. Your net worth will hopefully increase dramatically after you’ve renovated the property.


3. Fewer delays for approvals

When building new properties, you are exposed to outside influences that cause delays and usually lower your margins. Some good examples include when the approval on your construction plans does not go in your favor, when your developer was in charge of getting the permit but didn’t do it in time, or when your contractor made some error that resulted in a poorly built property. Situations of this nature make a bad situation worse. And the worst part is that they can all occur with the same property. Sometimes this will force you to make decisions that will seriously affect your bottom line.


This is not the case when you purchase a distressed home. The previous owners likely have already gone through this process, so you will not need to worry about getting government approvals and avoiding setbacks.


But best of all is the fact that you don’t have to deal with delay after delay. Sure, you’ll have someone renovate the property. But the complexity of getting an entire home built is far greater than doing some renovations. This has a major impact on the timelines you’re working with, so you’ll be making more money faster with distressed homes.


How do I find a distressed property?


The best place to start looking for distressed properties is at the bank or other financial institutions. Usually, they don’t have the time to advertise and seek out real estate agents or companies to market their properties.


You can also take a look at foreclosed properties from government-owned institutions, such as the Federal Housing Administration (FHA), the U.S. Department of Veterans Affairs, or the Internal Revenue Services Department (IRS), to name a few. Usually, these institutions will advertise their properties in the newspapers.


Another way to find distressed properties is to do a simple Google search for properties in your area that are on auction or up for foreclosure. You can look for online public records at the county courthouse, which records and stores real estate transactions for property in that county. Make sure to check Craigslist daily, and try sending out some yellow letters.


Finally, it is always best to contact an experienced real estate investor specializing in this area to guide and advise you on your purchase. Apart from the fact that successful real estate investors have access to all kinds of lists, you can take advantage of their networks and connections to banks, mortgage companies, and real estate agencies.


Can you finance a distressed property?


Financing any investment property can be difficult. Distressed properties are even more difficult to finance, but it can be done.


One option is to get a conventional mortgage if the home is in livable condition. To get one, you will need to prove to the bank that you are trustworthy, meaning you must have excellent credit, low debt, and a solid income. You must also be able to provide a large down payment.


Non-traditional lenders may be more likely to finance distressed properties. You can look to friends and family who may be willing to loan you money, or you can look to private groups and clubs interested in real estate and/or investing.


If you have a good track record as a real estate investor, you may be able to get a short-term hard money loan, sometimes known as a “fix-and-flip” loan. You won’t need as high of a credit score or down payment for this option, but the interest rates are higher than those of conventional loans.


If none of these options work for you, you can try to use the equity of your primary residence as collateral to put in an offer and then purchase a distressed property. You can do this through refinancing, which will allow you to borrow more than what you owe on your property and use the excess money to invest in a distressed property.


Now that you have all the facts, you are in a better position to own your first distressed home in the future. Often the difference between a successful real estate mogul and a failure is not one’s better abilities or ideas but the courage to bet on ideas, take a calculated risk, and act.


Most of all, it will come down to your ability to sniff out the perfect opportunity. That means the highest chances of getting your bid accepted, the right location, and manageable renovations. All these things factor into what makes a great deal or not.


It’s important to remember that you’re looking for an undervalued property—not just a cheap one. You can buy a $60,000 property for $10,000 and still end up with a loss. Some deals just never make sense, and if you understand that, you’ll love what distressed properties have to offer.

Source: Bigger Pockets Blog


Dusty Rhodes Properties is the Best Realtor in Myrtle Beach! We do everything in our power to help you find the home of your dreams. With experience, expertise, and passion, we are the perfect partner for you in Myrtle Beach, South Carolina. We love what we do and it shows. With more than 22 years of experience in the field, we know our industry like the back of our hands. There’s no challenge too big or too small, and we dedicate our utmost energy to every project we take on. We search thousands of the active and new listings from Aynor, Carolina Forest, Conway, Garden City Beach, Longs, Loris, Murrells Inlet, Myrtle Beach, North Myrtle Beach, Pawleys Island, and Surfside Beach real estate listings to find the hottest deals just for you!

Share
Questions to Ask Before Hiring a Real Estate Agent
By Dusty Rhodes • November 2, 2026
Know what to ask before hiring a real estate agent. Learn to evaluate experience, qualifications, local knowledge, marketing, and negotiation skills in Myrtle Beach.
By Dusty Rhodes • October 19, 2026
If you're thinking about selling a home, you may be wondering: “Can I negotiate the real estate commission?” The short answer is yes, real estate commissions and agent compensation can be negotiable. But there's a lot more to the question than simply asking an agent to lower their fee. Before negotiating real estate commission rates, it's important to understand what you're actually negotiating, what services are included, how the compensation is structured, and whether a lower fee could affect the marketing, service, negotiation, or overall strategy you receive. As a Myrtle Beach real estate agent , I think homeowners should absolutely understand how real estate compensation works before choosing an agent. You should know what you're paying for, what services are included, and what you can reasonably expect from your agent. Here's what you need to know about negotiating real estate commission rates. Can You Negotiate Real Estate Commission? Yes. Real estate commissions are negotiable. There isn't one universally required commission rate that every real estate agent must charge. Compensation is something the parties can discuss and agree upon as part of the representation agreement. That means you can ask an agent: Is your commission negotiable? What services are included? What does your fee cover? Are there different service options? What marketing do you provide? How is buyer-agent compensation handled? Are there additional fees? What would change if I negotiated a different fee? Those are reasonable questions. In fact, I think homeowners should ask them. The important thing is to understand the entire value proposition rather than focusing exclusively on the percentage. Why Do Real Estate Agents Charge a Commission? Before negotiating a real estate commission, it helps to understand what the commission is actually paying for. A real estate agent's compensation can cover a significant amount of work before, during, and after the transaction. For a seller, that may include: Preparing a pricing strategy Performing a comparative market analysis Advising on property preparation Professional photography Marketing MLS exposure Digital advertising Social media marketing Showing coordination Buyer-agent communication Offer analysis Negotiation Inspection negotiations Appraisal issues Transaction coordination Communication with attorneys, lenders, inspectors, and other professionals Managing deadlines Problem solving Getting the transaction to closing And much of that work happens behind the scenes. The commission isn't simply a fee for putting a property on the MLS. How Much Is the Typical Real Estate Commission? There is no single standard real estate commission that every agent charges. Compensation can vary based on: The agent The brokerage The property The market The services provided The complexity of the transaction The agreement between the parties That's why you shouldn't assume that every Myrtle Beach real estate agent charges the same amount. You also shouldn't assume that two agents charging the same percentage are providing the same level of service. One agent may provide extensive marketing, professional photography, video, advertising, frequent communication, and hands-on transaction management. Another may offer a much more limited service model. The percentage alone doesn't tell you the whole story. What Does a Real Estate Commission Actually Pay For? This is one of the most important questions to ask. Instead of simply asking: “Can you lower your commission?” I'd recommend asking: “What do I receive for your fee?” For a seller, the answer might include: Pricing Strategy Your agent researches comparable properties and helps establish a pricing strategy based on the current market. Marketing Your home may be marketed through the MLS, online platforms, social media, photography, video, advertising, open houses, and agent-to-agent outreach. Negotiation Your agent helps evaluate offers and negotiate price and terms. Transaction Management Your agent helps keep the transaction moving after you accept an offer. Problem Solving When something unexpected happens, your agent helps you understand your options and communicate with the appropriate parties. Local Expertise An experienced local agent can provide insight into neighborhoods, buyer behavior, market conditions, and pricing that isn't necessarily obvious from an online home-value estimate. When you're comparing agents, these services matter. Can I Ask a Realtor to Lower Their Commission? Absolutely. There's nothing wrong with asking. A professional conversation might be: “Is there any flexibility in your compensation?” That's a reasonable question. However, you should also expect the agent to explain what their compensation covers and why they charge what they charge. If an agent agrees to reduce their fee, you should understand whether anything else changes. For example: Does the marketing change? Are professional photos still included? Is video included? Are advertising services reduced? Does the level of communication change? Are certain services no longer included? Is there a different service package? Does the agent's availability change? A lower fee isn't necessarily a problem. But you should know what you're getting in exchange. Should I Always Choose the Real Estate Agent With the Lowest Commission? I wouldn't. If you're selling a $500,000 home, the difference between two compensation structures may look significant on paper. But the real question should be: Which agent is most likely to help me achieve the best overall outcome? Suppose one agent charges slightly less but provides limited marketing and doesn't negotiate aggressively. Another agent charges more but has a strong marketing strategy, excellent communication, extensive local knowledge, and a proven ability to negotiate. The cheaper agent isn't necessarily cheaper in the end. A difference in sale price, concessions, repairs, or contract terms can potentially be much larger than the difference in the agent's fee. That's why I encourage sellers to look at net results and overall value , not just commission percentage. How Does Commission Negotiation Affect a Seller's Net Proceeds? This is where the conversation gets interesting. Let's say your home sells for $500,000. A lower commission rate may reduce the amount paid to your agent. But what matters to you as the seller is ultimately: How much money do I walk away with? For example, an agent who helps you achieve a stronger sale price, negotiate better terms, minimize unnecessary concessions, and avoid costly mistakes may create significantly more value than the difference between two commission rates. That's why I believe the better question isn't: “Who charges the least?” It's: “Who can provide the best overall value and help me reach my goals?” Can Real Estate Agents Offer Different Fee Structures? In some situations, agents may offer different compensation or service structures. The possibilities depend on the agent, brokerage, transaction, and services being provided. For example, an agent may structure services differently depending on whether the client wants: Full-service representation A more limited service arrangement Additional marketing Specialized marketing for a luxury property Different levels of advertising Other negotiated services The important thing is to get the agreement in writing so everyone understands exactly what is included. What About Buyer-Agent Compensation? This is an area that has changed significantly in recent years. Buyers working with a real estate agent generally enter into a written buyer representation agreement that addresses the agent's compensation. The amount and structure of that compensation should be clearly explained before you begin working together. In some transactions, the seller may agree to contribute toward the buyer agent's compensation. In others, the buyer may be responsible for some or all of it. The important point is that buyers should understand their agreement before making an offer , rather than assuming someone else will automatically pay their agent. If you're buying a home in Myrtle Beach, ask your agent: How are you compensated? What does our agreement say? What happens if the seller doesn't offer compensation? What would I potentially be responsible for? Can your compensation be negotiated? What services are included? These are all fair questions. Is Real Estate Commission Negotiable for Buyers Too? Potentially, yes. Buyer-agent compensation is addressed in the buyer representation agreement, and compensation can be negotiated between the parties. However, buyers should focus on the complete representation they're receiving. A buyer's agent may help with: Finding properties Market research Property analysis Neighborhood knowledge Offer strategy Contract negotiations Inspection negotiations Due diligence Appraisal issues Communication with the listing agent Transaction management Getting the buyer to closing Again, the lowest fee isn't automatically the best deal. What Should I Ask a Real Estate Agent Before Negotiating Commission? I f you're interviewing agents, I'd recommend asking these questions. 1. What is your compensation? Start with the obvious. You should know exactly what the agent is proposing. 2. What services are included? Don't assume every agent provides the same services. 3. What marketing will you provide? Ask specifically about: Photography Video MLS Social media Online advertising Open houses Email marketing Property websites Other promotional efforts 4. Are there additional fees? Ask whether there are any additional costs beyond the agreed compensation. 5. What happens if I negotiate a lower fee? If the agent offers a different rate, ask whether the services or marketing change. 6. How will you help me determine the right price? Pricing can have a major impact on the outcome. 7. How do you negotiate? Ask the agent how they approach offers, inspections, repairs, appraisal issues, and other negotiations. 8. How much experience do you have in my market? Local knowledge matters. Can I Negotiate a Real Estate Agent's Commission After Signing? This is where you need to be careful. Once you've entered into a written representation agreement, you shouldn't assume you can simply change the compensation whenever you want. Any changes should be discussed with your agent and properly documented according to the terms of your agreement and applicable law. That's why it's important to understand the agreement before you sign it. Don't be afraid to ask questions. If something isn't clear, ask your agent to explain it. Why Would a Real Estate Agent Agree to a Lower Commission? Every situation is different. An agent may consider factors such as: The expected sale price Property type Location Expected workload Marketing requirements Whether the client is buying and selling Multiple transactions Timing Complexity of the transaction But an agent also has real business expenses. Those can include: Brokerage fees MLS expenses Marketing Photography Signs Technology Insurance Licensing Vehicle expenses Advertising Administrative support Taxes And unlike a salaried employee, a real estate agent generally doesn't get paid simply for showing up. Compensation is tied to the transaction. That's something worth keeping in mind when evaluating a fee. Does a Lower Commission Mean Less Service? Not necessarily. Some agents may be willing to negotiate without reducing their service. Others may have different service levels or adjust what's included. That's why you should never assume. Ask. If an agent agrees to reduce their fee, ask: “Will anything about your marketing or services change?” Get the answer clearly understood before moving forward. What About Flat-Fee Real Estate Agents? You may also come across agents or companies advertising a flat fee instead of a percentage-based commission. This can sound attractive because you know the cost upfront. But once again, compare the entire service package . Ask: What exactly is included? Who handles showings? Who negotiates? Who handles inspections? Who communicates with the buyer's agent? Who manages the transaction? Is professional photography included? Is advertising included? What happens if the transaction becomes complicated? A lower upfront fee may be appropriate for some sellers. For others, full-service representation may provide more value. There's no one-size-fits-all answer. What I Would Look At If I Were Selling a Home If I were interviewing agents to sell my own home, I wouldn't make commission the first question. I'd want to know: 1. How would you price my house? 2. What is your marketing plan? 3. How will you get buyers' attention? 4. How well do you know my neighborhood? 5. How do you handle negotiations? 6. What happens when something goes wrong? 7. How will you communicate with me? 8. What exactly is included in your compensation? 9. Are there additional fees? 10. What do you believe you can do for me that another agent can't? Then I'd look at the compensation. That's because I want to know what I'm getting before deciding what I'm willing to pay. Real Estate Commission Negotiation in Myrtle Beach The Myrtle Beach real estate market has its own set of considerations. The Grand Strand isn't one single market. There are major differences between: Myrtle Beach North Myrtle Beach Carolina Forest Conway Surfside Beach Murrells Inlet Socastee Market Common Grande Dunes Barefoot Resort Golf communities Intracoastal Waterway communities Oceanfront and second-home properties The type of property you're selling can also affect the marketing strategy. Selling a primary residence in Carolina Forest isn't the same as selling an oceanfront condo. Selling a luxury home isn't the same as selling an entry-level property. That's why I believe compensation should always be considered alongside the specific strategy and service you're receiving. The Real Question Isn't “Can I Get a Lower Commission?” Yes, you can ask. But I'd encourage you to take the conversation one step further. Instead of asking only: “Can you lower your commission?” Ask: “What value am I getting for your fee?” That's a much better conversation. Because ultimately, your goal isn't to hire the cheapest real estate agent. Your goal is to make the best financial decision possible. For a seller, that means looking at the entire transaction: Sale price + negotiation + marketing + terms + service + expenses = your overall result. And for a buyer: Representation + negotiation + guidance + market knowledge + transaction management = the value of your agent. My Perspective as a Myrtle Beach Real Estate Agent I've been in the real estate business for more than 10 years, and one thing I've learned is that every client and every transaction is different. I don't expect someone to hire me simply because I'm an agent. I expect them to ask questions. I want clients to understand what they're paying for, what services I provide, how I approach the market, and what I believe I can do for them. And if someone wants to discuss compensation, I'm happy to have that conversation. I think that's how it should work. At the same time, I don't believe the lowest commission automatically equals the best deal. If I'm selling your home, my goal isn't just to get it listed. It's to help you develop the right strategy, attract qualified buyers, negotiate effectively, navigate the transaction, and ultimately get you to the closing table with the best overall outcome I can reasonably help you achieve. Frequently Asked Questions About Real Estate Commission Negotiation Can you negotiate real estate commission? Yes. Real estate compensation is negotiable, and the specific terms should be discussed and documented in the applicable representation agreement. What is a reasonable real estate commission? There isn't one universally required commission rate. Compensation varies based on the agent, services, transaction, property, and agreement between the parties. Can I negotiate my Realtor's commission? You can ask whether the agent is willing to negotiate their compensation. If changes are agreed upon, make sure you understand what services are included and get the terms in writing. Should I choose a real estate agent based on commission? I wouldn't recommend choosing an agent based solely on commission. Consider experience, local knowledge, marketing, communication, negotiation skills, service, and overall value. Can buyer-agent compensation be negotiated? Yes. Buyer-agent compensation is addressed through the buyer representation agreement and can be negotiated. Buyers should understand exactly what they may be responsible for before entering into an agreement. Can a seller negotiate what they pay toward buyer-agent compensation? The seller and buyer can negotiate transaction terms, including whether the seller is willing to contribute toward the buyer's agent compensation, where permitted and agreed upon. What should I ask before agreeing to a real estate commission? Ask what services are included, how the property will be marketed, whether there are additional fees, how negotiations are handled, and whether anything changes if the compensation is adjusted. The Bottom Line: Can You Negotiate Real Estate Commission Rates? Yes, you can negotiate real estate commission rates and agent compensation. But don't stop at the percentage. Ask what you're actually receiving for the fee. Compare agents based on: Experience Local market knowledge Marketing Communication Negotiation Service Transaction management Problem solving Overall value A lower commission may save you money. But the right agent may also help you make more money, avoid costly mistakes, negotiate better terms, and navigate problems that could otherwise cost you significantly more. The goal shouldn't be to pay the lowest possible fee. The goal should be to get the best overall value for the money you're paying. If you're thinking about selling a home in Myrtle Beach, Carolina Forest, North Myrtle Beach, Conway, Surfside Beach, Murrells Inlet, or anywhere along the Grand Strand , I'd be happy to sit down with you, explain how I approach the sale, and answer your questions about compensation and services. You don't have to make a decision simply because we talk. You should have enough information to decide whether I'm the right agent for you.
What Does a Real Estate Agent Actually Do?
By Dusty Rhodes • October 5, 2026
What does a real estate agent actually do? Learn the responsibilities of a buyer's or listing agent and how a Myrtle Beach REALTOR® helps from start to closing.