What Stays With the House When You Move?
When you’re selling your home, it is natural to assume that anything you can safely remove is yours to keep—like the light fixtures you painstakingly cleaned and repaired, or the appliances you bought last year.
But the truth is, the buyer may want some of those items, too, and sometimes it's better to part ways with these items for the sake of the sale.
Rather than keep everything, you should decide what you'd like to keep and what you'll leave behind as a way to entice buyers into making an offer, particularly in today's market where buyers are holding more of the cards than ever.
What stays with the house?
Generally, certain items stay with the house when you sell and move. Some features may seem obvious, but the truth is, you're probably expected to leave more behind than you think. Some of these items can include:
- Built-ins: Built-in bookshelves, benches, and pull-out furniture generally stay inside the home.
- Landscaping: Trees, shrubs, and any flowers planted in the ground should stay in the yard.
- Wall mounts: If you have TV wall mounts or picture mounts that might damage the wall if you remove them, it is a good idea to leave them in place when you move.
- Custom-fit items: If you have custom-made curtains, plantation shutters, or blinds, leave them on the windows and doors.
- Hardware: If you upgraded the knobs and drawer pulls in the bathrooms and kitchen, you should either leave those behind or install replacements before you move.
- Alarm systems: Wireless alarm systems are designed to be removed. Otherwise, leave the alarm monitoring station attached and either relocate or cancel the monitoring service.
- Smoke detectors: Smoke detectors and sprinkler systems should stay in the house, especially if you plan to move before selling the house.
What can you take?
While you’re expected to leave some items behind, in general your belongings are yours to keep. Here are some examples:
- Patio furniture, lawn equipment, and play sets: If you have a wooden swing set in the backyard and a bistro table on the front porch, take those items with you.
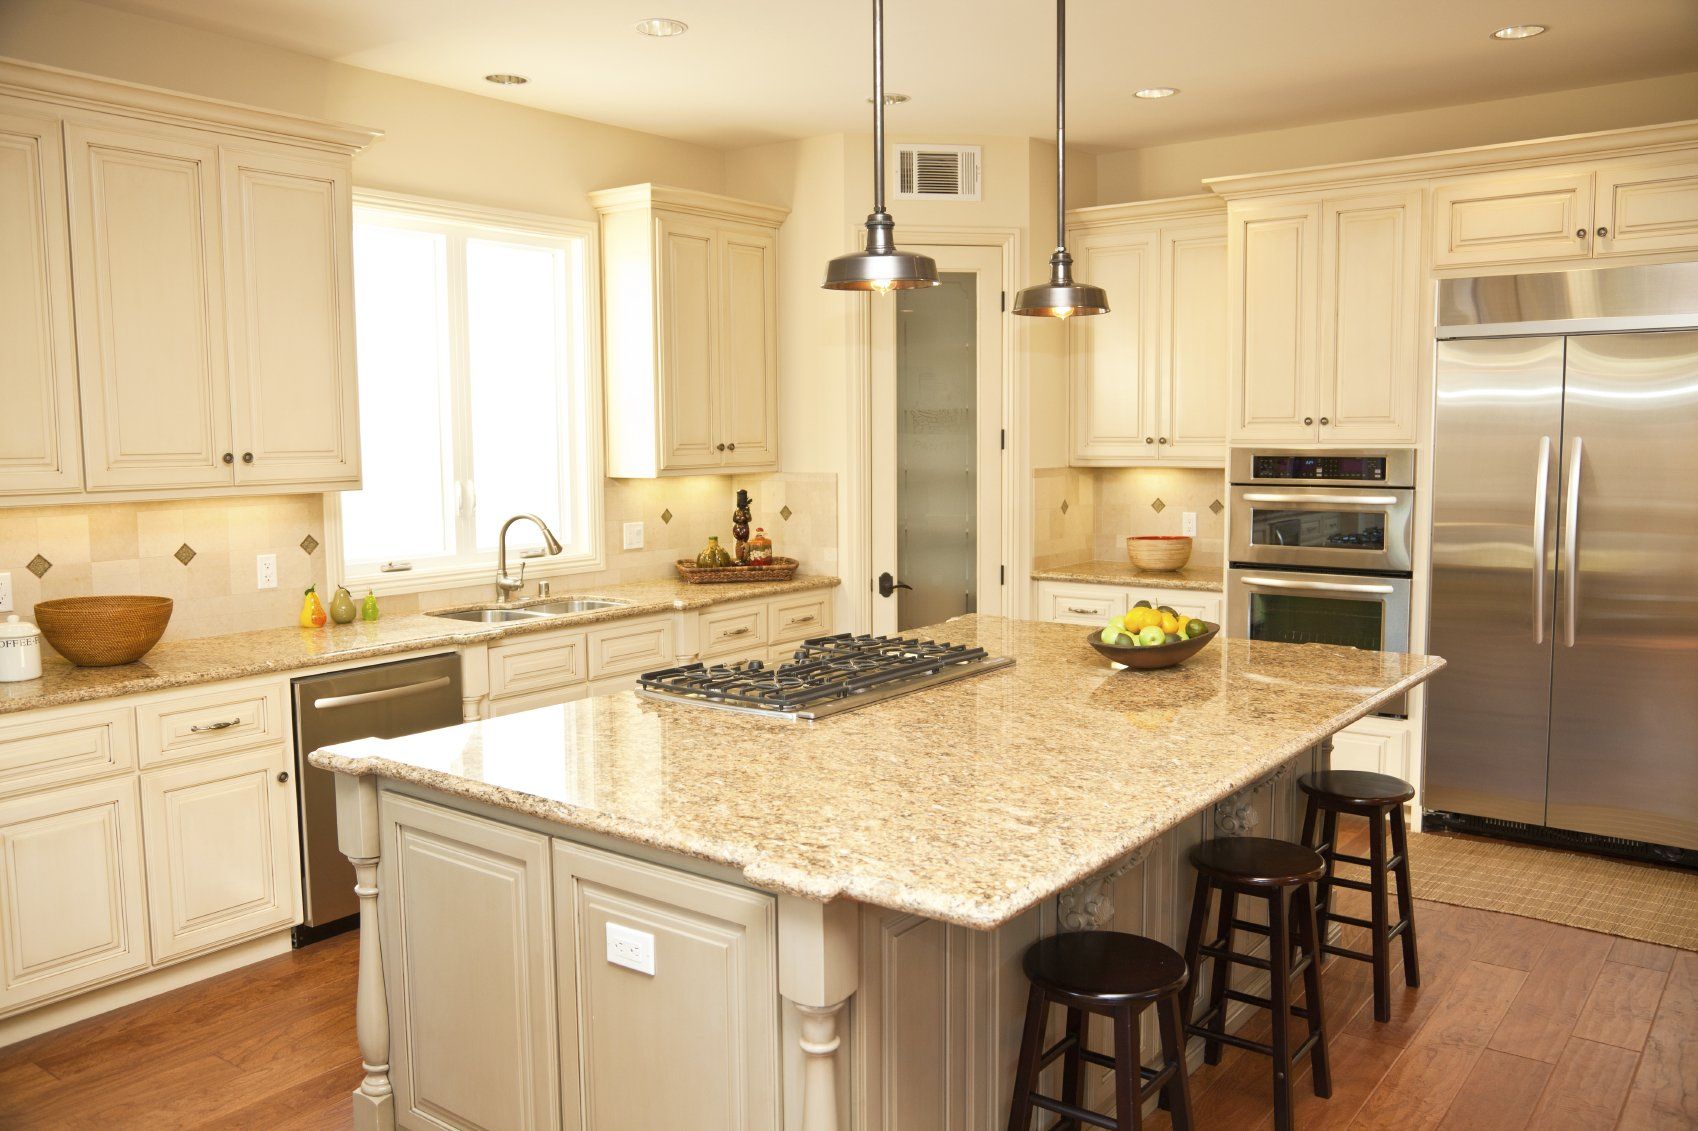
- Appliances: Some lenders require that a home have an oven installed before approving a loan, but for all other appliances, it's up to you to decide what you will take and what you will offer as part of the home.
- Some light fixtures: Generally, homeowners leave light fixtures behind, but if you’re attached to a certain fixture, you can make arrangements with the buyer to take it.
- Built-in kitchen tools: If you can safely remove a mounted spice rack or the pasta arm, you can take it with you.
- Rugs, basic curtains, wreaths: Small decor items like rugs or curtain rods that can be safely removed can be taken.
What should you consider leaving?
Some of your personal items can be used to help sell your house—or increase the asking price. Before you take everything just to take it, consider offering some hot items like the following:
- Appliances: Homeowners, especially new homeowners, don’t always have their own appliances. Many buyers would be more likely to place an offer on a home if it came fully stocked with appliances.
- Custom swing and play sets: If you have a swing set or playhouse your children have outgrown and you notice a potential buyer has children, offer to include the item with the deal.
- Kitchen built-ins: Built-in spice racks, pantry organization, and windowsill shelves can really help sell a kitchen. Consider offering the items to an interested buyer.
- Light fixtures, curtains, rugs, and other upgrades: If you’ve upgraded the light fixtures or have custom rugs in the entryway, a buyer may be willing to increase his or her offer to keep those items in the home.
If you’re not sure what would entice a buyer, ask your real estate agent to provide suggestions. Don't have an agent yet? Here's how to find a real estate agent in your area.
Source:
Realtor.com
Dusty Rhodes Properties is the Best Realtor in Myrtle Beach! We do everything in our power to help you find the home of your dreams. With experience, expertise, and passion, we are the perfect partner for you in Myrtle Beach, South Carolina. We love what we do and it shows. With more than 22 years of experience in the field, we know our industry like the back of our hands. There’s no challenge too big or too small, and we dedicate our utmost energy to every project we take on. We search thousands of the active and new listings from Aynor, Carolina Forest, Conway, Garden City Beach, Longs, Loris, Murrells Inlet, Myrtle Beach, North Myrtle Beach, Pawleys Island, and Surfside Beach real estate listings to find the hottest deals just for you!
Share